



 Chat with AI
Exam 11: Consolidation: Intragroup Transactions

Exam 1: Nature and Regulation of Companies50 Questions
Exam 2: Financing Company Operations62 Questions
Exam 3: Business Combinations50 Questions
Exam 4: Disclosure: Legal Requirements and Accounting Polices50 Questions
Exam 5: Disclosure: Presentation of Financial Statements50 Questions
Exam 6: Disclosure: Statement of Cash Flows20 Questions
Exam 7: Foreign Currency Transactions and Forward Exchange Contracts20 Questions
Exam 8: Translation of Financial Statements Into a Presentation Currency30 Questions
Exam 9: Consolidation: Controlled Entities50 Questions
Exam 10: Consolidation: Wholly Owned Subsidiaries50 Questions
Exam 11: Consolidation: Intragroup Transactions50 Questions
Exam 12: Consolidation: Non-Controlling Interest50 Questions
Exam 13: Consolidation: Other Issues50 Questions
Exam 14: Associates and Joint Ventures48 Questions
Exam 15: Joint Arrangements29 Questions
Exam 16: Insolvency and Liquidation50 Questions
Exam 17: Accounting for Company Income Tax20 Questions
Exam 18: Property, Plant Equipment50 Questions
Select questions type


A subsidiary entity sold goods to its parent entity for $100 000. The inventories originally cost the subsidiary $125 000. At reporting date, the parent still held all of the inventories. Which of the following adjustments must be included as part of the consolidation entry to eliminate this transaction?
(Multiple Choice)
5.0/5  (77)
(77) Unrealised profit in the opening inventories of a financial period is adjusted in the consolidation worksheet by a:
(Multiple Choice)
4.9/5 (85)
(85) When an interest bearing loan is advanced by a parent to a subsidiary, a credit is required on consolidation against the loan payable and interest revenue accounts.
(True/False)
4.9/5 (82)
(82) Thurston Limited sold inventories to its parent entity, Cowboys Ltd, at a before-tax profit of $8000. The inventories originally cost Thurston Limited $32 000. At balance sheet date, Cowboys Limited had sold 90% of the inventory to an external party. The consolidation adjustment entry (excluding tax effects) will eliminate unrealised profit amounting to:
(Multiple Choice)
4.9/5 (104)
(104) Which of the following intragroup transactions do not affect the carrying amounts of assets and liabilities?
(Multiple Choice)
4.8/5 (70)
(70) In May 2017, a parent sold inventories to a subsidiary entity for $60 000. The inventories had previously cost the parent entity $48 000. The entire inventory is still held by the subsidiary at reporting date, 30 June 2017. Ignoring tax effects, which of the following is the adjustment entry in the consolidation worksheet at reporting date? Cash 48000 Sales revenue 48000 Cost of sales 48000 Inventories 48000
Sales revenue 48000 Cash 48000 Inventories 48000 Cost of sales 48000
Cost of sales 60000 Sales revenue 12000 Inventories 48000
Sales revenue 60000 Cost of sales 48000 Inventories 12000
(Short Answer)
5.0/5 (83)
(83) A subsidiary sold inventories to its parent in year 1 at a before-tax profit of $15 000. At balance sheet date, the parent had not sold the inventories to an external party. The company tax rate is 30%. The year 1 consolidation worksheet will contain which of the following adjustment entries for inventories?
(Multiple Choice)
4.8/5 (84)
(84) During the year ended 30 June 2017, a subsidiary sold inventories to a parent for $90 000. The inventories had previously cost the subsidiary entity $72 000. By 30 June 2017 the parent had sold 75% of the inventories to a party outside the group. The remaining inventories were sold externally in July 2017. The company tax rate is 30%. Which of the following is the adjustment entry in the consolidation worksheet at 30 June 2018? Sales revenue 90000 Cost of sales 85500 Inventories 4500 Deferred tax asset 1350 Income tax expense 1350
Retained earnings 4200 Income tax expense 1800 Cost of sales 6000 Retained earnings Income tax expense 3150 Cost of sales 1350 4500
Retained earnings 4500 Inventories 4500 Deferred tax asset 1350 Retained earnings 1350
(Short Answer)
4.7/5 (86)
(86) Sky Limited, a subsidiary entity, sold a non-current asset at a profit to its parent entity, Dive Limited. The adjustment necessary on consolidation to reflect the tax effect of this transaction will result in a(n):
(Multiple Choice)
4.9/5 (72)
(72) Where an intragroup sale of an asset has been made and the asset was classified as inventories in the selling entity's books, but subsequently classified as plant in the buying entity's books, all depreciation recognised in the buying entity's books must be eliminated on consolidation.
(True/False)
4.8/5 (86)
(86) A subsidiary sold inventories to its parent for $40 000. The inventories originally cost the subsidiary $32 000. At balance sheet date, the parent had 20% of the inventories still on hand. The consolidation adjustment entry (excluding tax effects) will eliminate unrealised profit amounting to:
(Multiple Choice)
4.8/5 (82)
(82) Abra Ltd sold an item of plant to its subsidiary Cadabra Ltd on 1 January 2017 for $50 000. The asset had cost Abra Ltd $60 000 when acquired on 1 January 2015. At that time the useful life of the plant was assessed at 6 years. Rounded to the nearest dollar, the consolidation elimination entries at 30 June 2017 in relation to the sale of plant are which of the following? 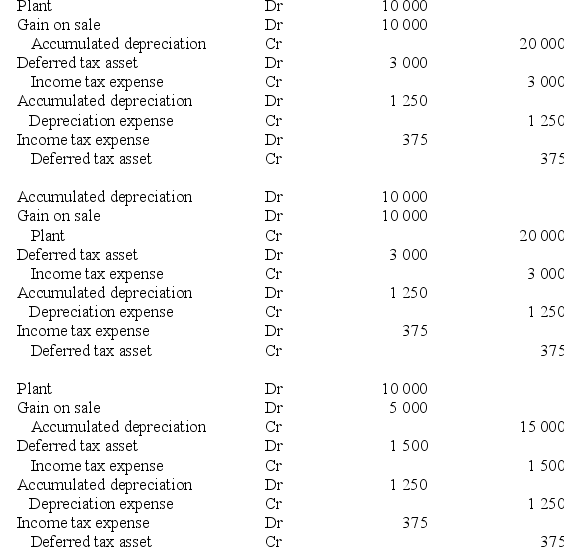 Accumulated depreciation 15000 Gain on sale 5000 20000 Plant Deferred tax asset 1500 Income tax expense 1500
Accumulated depreciation 1250 Depreciation expense 1250 Incometax expense 375 Deferred tax asset. 375
Accumulated depreciation 15000 Gain on sale 5000 20000 Plant Deferred tax asset 1500 Income tax expense 1500
Accumulated depreciation 1250 Depreciation expense 1250 Incometax expense 375 Deferred tax asset. 375
(Short Answer)
4.9/5 (87)
(87) AASB 10/IFRS 10 Consolidated Financial Statements requires that intragroup transactions be:
(Multiple Choice)
4.8/5 (76)
(76) The effect of an intragroup sale of inventories in a prior period, where the inventories are still on hand at the end of that prior period, is that a debit consolidation adjustment is made to opening retained earnings.
(True/False)
4.7/5 (75)
(75) Where a dividend is declared in a prior period and paid in a current period, the credit in the consolidation elimination entry is made against the dividend declared/paid account.
(True/False)
4.8/5 (86)
(86) When an entity sells a non-current asset at a profit to another entity within the same group, which of the following adjustments is necessary on consolidation?
(Multiple Choice)
4.8/5 (85)
(85) When a depreciable non-current asset is sold between entities within a group, any gain recognised on the sale is eliminated and realised through future use of the asset by the group.
(True/False)
4.9/5 (73)
(73) Tax effect consolidation entries are not required when intragroup services are provided to entities within a group.
(True/False)
4.9/5 (80)
(80) The effect of an intragroup sale of inventories at a profit, where the inventories have been sold to external parties prior to the end of the reporting period, is that both profit and the inventories asset are overstated.
(True/False)
4.9/5 (83)
(83) Unite Ltd provided a loan of $1 000 000 to its subsidiary Inspire Ltd. Interest of $100 000 was charged during the year ended 30 June 2018. On consolidation, which of the following adjustments is needed at 30 June 2018 in relation to the interest charged?
(Multiple Choice)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)