



 Chat with AI
Exam 18: Accounting for Leases

Exam 11: Current Liabilities and Contingencies83 Questions
Exam 12: Non-Current Financial Liabilities83 Questions
Exam 13: Equities75 Questions
Exam 14: Complex Financial Instruments89 Questions
Exam 15: Earnings Per Share98 Questions
Exam 16: Accounting for Income Taxes85 Questions
Exam 17: Pensions and Other Employee Future Benefits96 Questions
Exam 18: Accounting for Leases95 Questions
Exam 19: Statement of Cash Flows58 Questions
Select questions type


Here are the terms of a lease agreement:
Fair value of leased asset 500,000 Lease term 15 years Payment frequency Annual Payment timing End of year Guaranteed residual value 0 Interest rate implicit in lease (known to lessee) 5\% Lessee's incremental borrowing rate 5\% Requirement:
Determine the amount of lease payment that the lessor would require to lease the asset.

Free
(Essay)
4.9/5  (78)
(78) Correct Answer: Verified
Computation of required lease payments 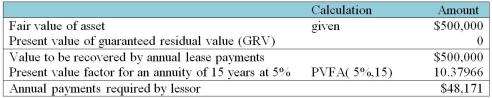 Using BAII Plus: 15 N,5 I/Y,-500,000 PV,CPT PMT
Which statement is correct about the "guaranteed residual value"?
Free
(Multiple Choice)
4.7/5 (73)
(73) Correct Answer:Verified
VerifiedC
Under IFRS,assuming all information is available,which rate is used by the lessee in the minimum lease calculation?
(Multiple Choice)
4.7/5 (87)
(87) For the following lease,determine the minimum lease payments for the lessee. Annual lease payment at the end of the end \ 23,104 Lease term 5 Incremental rate 10\% Implicit rate (unknown to lessee) 8\% Unguaranteed residual value 10,000 Guaranteed residual value 20,000
(Multiple Choice)
4.7/5 (71)
(71) Here are the terms of a lease agreement:
Fair value of leased asset 50,000 Lease term 4 years Payment frequency Annual Payment timing End of year Guaranteed residual value 25,000 Interest rate implicit in lease (known to lessee) 5\% Lessee's incremental borrowing rate 8\% Requirements:
a.Determine the amount of lease payment that the lessor would require to lease the asset.
b.Compute the present value of minimum lease payments for the lessee.
(Essay)
4.8/5 (80)
(80) For the following lease,determine the minimum lease payments for the lessee. Annual lease payment at the end of the end \ 23,104 Lease term 5 Incremental rate 10\% Implicit rate (unknown to lessee) 8\% Unguaranteed residual value 10,000 Guaranteed residual value 20,000
(Multiple Choice)
4.9/5 (77)
(77) The following amortization schedule is for a lease entered into at the start of fiscal 2011 for an asset that will be useful for 5 years.The company uses straight-line depreciation method.
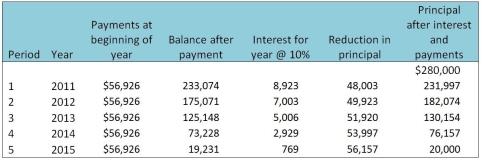 Required:
Provide the appropriate presentation of this lease in the lessee's balance sheet for December 31,2012,distinguishing amounts that are current from those that are non-current.
Required:
Provide the appropriate presentation of this lease in the lessee's balance sheet for December 31,2012,distinguishing amounts that are current from those that are non-current. (Essay)
4.8/5 (75)
(75) The following are some of the characteristics of an asset available for lease:
Fair value of leased asset 80,000 Useful life 10 years Lease term 7 years Payment frequency Annual Payment timing Beginning of year Guaranteed residual value 10,000 Interest rate implicit in lease (not known to lessee) 10\% Lessee's incremental borrowing rate 8\% Requirements:
a.Determine the amount of lease payment that the lessor would require to lease the asset.
b.Compute the present value of minimum lease payments for the lessee.
c.Compute the present value of minimum lease payments for the lessor.
d.Evaluate whether the lessee should classify the lease as operating or capital lease using the quantitative guidelines in ASPE.
(Essay)
4.8/5 (73)
(73) For the following lease,determine the minimum lease payments for the lessor. Annual lease payment at the end of the end \ 32,000 Lease term 5 Incremental rate 11\% Implicit rate (knownto lessee) 9\% Executory costs 10,000
(Multiple Choice)
4.8/5 (74)
(74) For the following lease,determine the minimum lease payments for the lessor. Annual lease payment at the end of the end \ 23,000 Lease term 5 Incremental rate 10\% Implicit rate (knownto lessee) 8\% Unguaranteed residual value 5,000 Guaranteed residual value 00,000
(Multiple Choice)
4.8/5 (82)
(82) On January 1,2011,Teddy Company sold a building to Breezy Bank for $40,000,000 and immediately leased it back under a 25-year non-cancellable lease at $3,208,000 per year,payable at the beginning of each year.Breezy used an implicit rate of 7% to determine the lease payments,and this rate is known to Teddy.The building had a carrying value of $12,000,000 on Teddy's books.
Requirement:
Assume that the lease is a finance lease for both the lessee and lessor,and there is no profit margin for the lessor.Prepare all necessary journal entries for 2011 for Teddy (the seller-lessee)and Breezy (the buyer-lessor).Teddy will continue to depreciate the building on a straight-line basis over the lease term.Explain the implications to Teddy's depreciation expense of this transaction.
(Essay)
4.9/5 (82)
(82) The following amortization schedule is for a lease entered into at the start of fiscal 2012 for an asset that will be useful for 5 years.The company uses straight-line depreciation method.
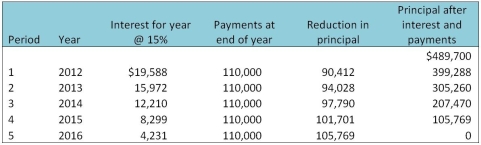 Required:
Provide the appropriate presentation of this lease in the lessee's balance sheet for December 31,2013,distinguishing amounts that are current from those that are non-current.
Required:
Provide the appropriate presentation of this lease in the lessee's balance sheet for December 31,2013,distinguishing amounts that are current from those that are non-current. (Essay)
4.9/5 (80)
(80) Viribana Corporation started operations on March I,2009.It needs to acquire a special piece of equipment for its manufacturing operations.It is evaluating two options as follows.
Option 1: Lease the equipment for 10 years.Lease payments would be $11,200 per year,due at the beginning of each fiscal year (March I).Viribana's incremental borrowing rate is 12%.There is no bargain purchase or renewal option.Viribana is responsible for all executory costs of operating the equipment.
Option 2: Purchase the equipment for $71,000 by borrowing the full purchase amount at 12% over 10 years.This price is considered the fair value of the equipment.Payments are due at the end of each fiscal year (February 28).
The equipment has a useful life of 10 years and would be depreciated on a straight-line basis.No residual value is expected to exist at the end of 10 years.
Requirements:
a.Calculate the present value of the lease payments (Option 1).
b.Calculate the payment that would be required under the purchase option (Option 2).
c.Calculate and briefly discuss the financial impact of each option on the non-current assets,total liabilities,and net income of Viribana for the first year of operations.Assume all payments were made when due.Show your calculations.
d.Indicate which option you would recommend for Viribana.Provide one explanation to support your recommendation.
(Essay)
4.8/5 (76)
(76) For the following lease,determine the minimum lease payments for the lessor. Annual lease payment at the end of the end \ 22,000 Lease term 5 Incremental rate 10\% Implicit rate (unknown to lessee) 8\% Unguaranteed residual value 15,000
(Multiple Choice)
4.7/5 (76)
(76) The following are some of the characteristics of an asset available for lease:
Fair value of leased asset 150,000 Lease term 8 years Payment frequency Annual Payment timing Beginning of year Guaranteed residual value 25,000 Interest rate implicit in lease (not known to lessee) 9\% Lessee's incremental borrowing rate 8\% Requirements:
a.Determine the amount of lease payment that the lessor would require to lease the asset.
b.Compute the present value of minimum lease payments for the lessee.
(Essay)
4.9/5 (72)
(72) On January 1,2011,Sheldon Company sold a building to Breezy Board Bank for $52,000,000 and immediately leased it back under a 15-year non-cancellable lease at $5,918,000 per year,payable at the beginning of each year.Breezy Board used an implicit rate of 9% to determine the lease payments,and this rate is known to Sheldon.The building had a carrying value of $34,000,000 on Sheldon's books.
Requirement:
Assume that the lease is an finance lease for both the lessee and lessor for both the lessee and lessor,and there is no profit margin for the lessor.Prepare all necessary journal entries for 2011 for Sheldon (the seller-lessee)and Breezy Board (the buyer-lessor).Breezy Board will depreciate the building on a straight-line basis over the remaining useful life of 15 years.Explain the implications to Soldier's depreciation expense of this transaction.
(Essay)
4.8/5 (83)
(83) On July 1,2011,Janus Company leased equipment to Pluto Company.The terms of the lease are as follows:
Fair value of leased asset 60,000 Lease payments, due at end of lease term starting June 30,2012 12,000 Lease term 9 years Economic life of leased asset 10 years Guaranteed residual value 6,000 Lessee's incremental borrowing rate 15\% Pluto uses straight-line depreciation for its property,plant,and equipment,and its year-end is December 31.
Requirement:
Prepare the journal entries for the lease from July 1 through December 31.
(Essay)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)