



 Chat with AI
Exam 9: Perfect Competition

Exam 1: Introduction: What Is Economics163 Questions
Exam 2: The Key Principles of Economics199 Questions
Exam 3: Exchange and Markets136 Questions
Exam 4: Demand, supply, and Market Equilibrium280 Questions
Exam 5: Elasticity: a Measure of Responsiveness173 Questions
Exam 6: Market Efficiency and Government Intervention120 Questions
Exam 7: Consumer Choice: Utility Theory and Insights From Neuroscience116 Questions
Exam 8: Production Technology and Cost163 Questions
Exam 9: Perfect Competition165 Questions
Exam 10: Monopoly and Price Discrimination128 Questions
Exam 11: Market Entry and Monopolistic Competition114 Questions
Exam 12: Oligopoly and Strategic Behavior125 Questions
Exam 13: Controlling Market Power: Antitrust and Regulation84 Questions
Exam 14: Imperfect Information: Adverse Selection and Moral Hazard98 Questions
Exam 15: Public Goods and Public Choice97 Questions
Exam 16: External Costs and Environmental Policy109 Questions
Exam 17: The Labor Market and the Distribution of Income178 Questions
Exam 18: International Trade and Public Policy229 Questions
Select questions type


For oligopolistic industries the demand is more elastic than demand facing monopolistically competitive industries.
(True/False)
4.9/5  (79)
(79) Since the ice production is constant,the supply curve is vertical.
(True/False)
4.8/5 (84)
(84) If a firm is producing where marginal revenue is greater than marginal cost:
(Multiple Choice)
4.9/5 (62)
(62)  -Refer to Figure 9.7.This firm's short-run supply curve is the firm's:
 (Multiple Choice)
4.8/5 (81)
(81) Assume firms in an increasing-cost industry are currently making profits.Which of the following statements describes what will happen in the long run?
(Multiple Choice)
4.9/5 (80)
(80) The owner of Tie-Dyed T-shirts,a perfectly competitive firm,has hired you to give him some economic advice.He has told you that the market price for his shirts is $20 and that he is currently producing 200 shirts.At this output his MC is $20,his SAVC is $15 and his SATC is $25.What would you recommend to him?
(Multiple Choice)
4.8/5 (76)
(76) 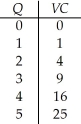 Table 9.3
-Table 9.3 shows the short-run cost data for the XYZ Widget Company.If widgets sell for $8 each and XYZ's total fixed costs equal $50,what will the firm do? Explain.
Table 9.3
-Table 9.3 shows the short-run cost data for the XYZ Widget Company.If widgets sell for $8 each and XYZ's total fixed costs equal $50,what will the firm do? Explain. (Essay)
4.8/5 (78)
(78)  -Refer to Figure 9.6.At a market price of $9,this perfectly competitive profit maximizing firm should produce ________ units.
 (Multiple Choice)
4.8/5 (74)
(74) Monopolistic industries are characterized by a homogeneous product.
(True/False)
4.8/5 (79)
(79) 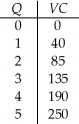 Table 9.2
-Consider a competitive firm that produces tomatoes.The fixed costs are $10 per bushel and the relationship between VC and output is shown in Table 9.2.Compute AVC and MC.How much output will be supplied if P = $45 and the firm wants to maximize profits? What if P = $55? What are profits if P = $60? What is the relationship between marginal cost,average variable cost,and the firm's supply curve?
Table 9.2
-Consider a competitive firm that produces tomatoes.The fixed costs are $10 per bushel and the relationship between VC and output is shown in Table 9.2.Compute AVC and MC.How much output will be supplied if P = $45 and the firm wants to maximize profits? What if P = $55? What are profits if P = $60? What is the relationship between marginal cost,average variable cost,and the firm's supply curve? (Essay)
4.8/5 (69)
(69) A milk company in a perfectly competitive industry is producing 10000 gallons of milk,its profit-maximizing quantity.Industry price for a gallon of milk is $3.50,total fixed costs are $5,000,and total variable costs are $10,000.The firm's economic profit is:
(Multiple Choice)
4.7/5 (76)
(76)  -Refer to Figure 9.3.If the market price of soybeans falls to $8,then to maximize profits this farmer should produce:
 (Multiple Choice)
4.8/5 (68)
(68) If a firm in a perfectly competitive market tries to raise its price above the going market price,then:
(Multiple Choice)
4.9/5 (94)
(94) Comment on the following statement: "When firms are earning positive profits,the industry supply curve will shift to the right."
(Essay)
4.8/5 (85)
(85) Toothpicks are sold in a perfectly competitive market.The market price is currently $3 per box of one hundred toothpicks.At its current level of production,a representative firm in the toothpick industry is producing at a level of output such that long-run average cost is $3.25 per box of one hundred toothpicks.Given this information,is the toothpick industry in equilibrium? Explain.
(Essay)
4.9/5 (99)
(99) In a perfectly competitive market,an individual firm cannot charge any price it wants.
(True/False)
4.8/5 (90)
(90) A perfectly competitive firm is producing 75 units of output.The market price is $7 and the firm's marginal cost is $8.The firm should:
(Multiple Choice)
4.8/5 (81)
(81) If there is an increase in demand in the long run for an increasing cost industry,the market price will fall.
(True/False)
4.7/5 (78)
(78)  -Refer to Figure 9.4.If the market price of hay falls to $18,then to maximize profits this farmer should produce:
 (Multiple Choice)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)