



 Chat with AI
Exam 14: Oligopoly

Exam 1: First Principles199 Questions
Exam 2: Economic Models: Trade-Offs and Trade299 Questions
Exam 4: Consumer and Producer Surplus229 Questions
Exam 3: Supply and Demand265 Questions
Exam 5: Price Controls and Quotas: Meddling With Markets216 Questions
Exam 6: Elasticity226 Questions
Exam 7: Taxes286 Questions
Exam 8: International Trade260 Questions
Exam 9: Decision Making by Individuals and Firms186 Questions
Exam 10: The Rational Consumer182 Questions
Exam 11: Behind the Supply Curve: Inputs and Costs317 Questions
Exam 12: Perfect Competition and the Supply Curve341 Questions
Exam 13: Monopoly317 Questions
Exam 14: Oligopoly271 Questions
Exam 15: Monopolistic Competition and Product Differentiation245 Questions
Exam 16: Externalities193 Questions
Exam 17: Public Goods and Common Resources208 Questions
Exam 18: The Economics of the Welfare State126 Questions
Exam 19: Factor Markets and the Distribution of Income316 Questions
Exam 20: Uncertainty, Risk, and Private Information192 Questions
Exam 21: Graphs in Economics60 Questions
Exam 22: Consumer Preferences and Consumer Choice135 Questions
Select questions type


In game theory,when a player has an action that is always best for that player,regardless of the action taken by the other player(s)in a game,we say this player has a _____ strategy.
(Multiple Choice)
4.8/5  (84)
(84) (Scenario: Two Identical Firms)Use Scenario: Two Identical Firms.If one firm decides to cheat,the cheating firm will: Scenario: Two Identical Firms
Two identical firms make up an industry in which the market demand curve is represented by Q = 5,000 - 4P,where Q is the quantity demanded and P is price per unit.The marginal cost of producing the good in this industry is constant and equal to $650.Fixed cost is zero.
(Multiple Choice)
4.7/5 (79)
(79) A firm that is in an oligopoly knows that its _____ affect its _____ and that the _____ of its rivals will affect it.
(Multiple Choice)
4.8/5 (65)
(65) Use the following to answer question: 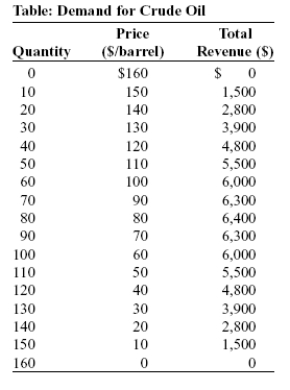 -(Table: Demand for Crude Oil)Use Table: Demand for Crude Oil.Assume that the crude oil industry is a duopoly and the marginal and fixed cost of producing crude oil equals zero.Suppose that the two firms are maximizing industry profit and splitting the profit evenly.If both firms decide to cheat and produce 10 more barrels each,firm 1's profit will be _____,and firm 2's profit will be _____.
 (Multiple Choice)
4.7/5 (73)
(73) To limit competition,oligopolists often practice product differentiation.
(True/False)
5.0/5 (82)
(82) Tacit collusion is likely to occur when firms have different market shares.
(True/False)
5.0/5 (79)
(79) Use the following to answer question:
Figure: Pricing Strategy in Cable TV Market I 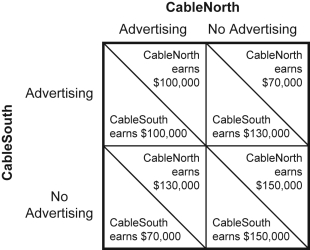 -(Figure: Pricing Strategy in Cable TV Market I)Use Figure: Pricing Strategy in Cable TV Market I.If the two firms in the cable TV market collude:
 (Multiple Choice)
4.8/5 (84)
(84) The purpose of the nineteenth-century cartels was to increase production and encourage price competition.
(True/False)
4.7/5 (80)
(80) A situation in which one firm sets the price and other firms in the industry match it is known as:
(Multiple Choice)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)