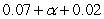Deck 28: The Heath-Jarrow-Morton Hjmand Libor Market Model LMM

Full screen (f)
exit full mode
Question
Which of the following is not a valid property of the Heath-Jarrow-Morton (HJM)interest-rate framework?

A)The model may be calibrated to be consistent with any initial yield curve.
B)The tree version of the model has rates of all remaining maturities at each node of the tree.
C)The model fits volatilities of rates of all maturities.
D)The model is a one-factor model.
Use Space or
up arrow
down arrow
to flip the card.
Question
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ,is given by the following binomial process: Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ,where the up and down movements are equiprobable.What is the Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> value for Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ?
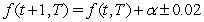
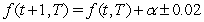
(a) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(b) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(c) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(d) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
Question
In the LMM,which of the following are martingales?

A)Libor rates.
B)Libor returns.
C)Zero-coupon rates.
D)Yields.
Question
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ,is given by the following binomial process: Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be
(a) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(b) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
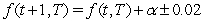
(c) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(d) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
Question
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year cap on the one-year forward rate at a strike rate of 7%.</strong> A)0.87 B)0.95 C)1.05 D)1.10 <div style=padding-top: 35px> ,is given by the following binomial process: <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year cap on the one-year forward rate at a strike rate of 7%.</strong> A)0.87 B)0.95 C)1.05 D)1.10 <div style=padding-top: 35px> ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year cap on the one-year forward rate at a strike rate of 7%.

A)0.87
B)0.95
C)1.05
D)1.10
Question
Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ,is given by the following binomial process with two shock terms: Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift ( Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> )for Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ?
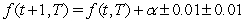
(a) Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(b) Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(c) Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(d) Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
Question
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year floor on the one-year forward rate at a strike rate of 7%.</strong> A)0.85 B)0.89 C)0.95 D)1.00 <div style=padding-top: 35px> ,is given by the following binomial process: <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year floor on the one-year forward rate at a strike rate of 7%.</strong> A)0.85 B)0.89 C)0.95 D)1.00 <div style=padding-top: 35px> ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year floor on the one-year forward rate at a strike rate of 7%.
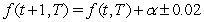
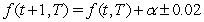
A)0.85
B)0.89
C)0.95
D)1.00
Question
Swap rates in the SMM are,under the risk-neutral forward measure

A)Normal.
B)Lognormal.
C)Exponential.
D)None of the above.
Question
The HJM model is implemented by depicting the evolution of which rates in particular?

A)Yields.
B)Zero-coupon rates.
C)Forward rates.
D)Discount functions.
Question
Which of the following is not necessarily a beneficial feature of the HJM binomial tree class of models?

A)The drift term is obtained in analytical form as a function of the volatilities.
B)The binomial tree carries the entire term structure of forward rates at each node.
C)The tree is recombining because the drift terms are available in analytical form.
D)The approach requires only drawing the tree out to the maturity of the option,and not to the maturity of bonds underlying a bond option.
Question
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a one-year put option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?</strong> A)1.00 B)1.26 C)1.54 D)1.67 <div style=padding-top: 35px> ,is given by the following binomial process: <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a one-year put option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?</strong> A)1.00 B)1.26 C)1.54 D)1.67 <div style=padding-top: 35px> ,where the up and down movements are equiprobable.What is the price of a one-year put option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?

A)1.00
B)1.26
C)1.54
D)1.67
Question
Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> .Each Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> -th forward rate has constant volatility Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> .For each forward period of one year what is the risk-neutral drift term in the Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> -th period equal to?
(a) Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(b) Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(c) Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(d) Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
Question
The numeraire in the Swap Market Model (SMM)is

A)The price of the longest maturity bond (i.e. ,the numeraire under forward measure).
B)The total of discount functions to the longest swap maturity.
C)The money market account.
D)The value of the fixed side of the swap.
Question
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a one-year call option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?</strong> A)0.50 B)0.55 C)0.60 D)0.65 <div style=padding-top: 35px> ,is given by the following binomial process: <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a one-year call option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?</strong> A)0.50 B)0.55 C)0.60 D)0.65 <div style=padding-top: 35px> ,where the up and down movements are equiprobable.What is the price of a one-year call option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?
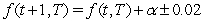
A)0.50
B)0.55
C)0.60
D)0.65
Question
In the HJM model,one of the striking features is that the risk-neutral drifts in the model are functions of only the

A)The forward rates.
B)The yields.
C)The volatility of forward rates.
D)The risk premia for interest-rate risk.
Question
In the Libor Market Model (LMM)which of the following is not a beneficial feature of the model?

A)The LMM only requires one factor for each rate.
B)The model is easily calibrated to the Black model caplet/floorlet prices.
C)The evolution of Libor rates is modeled directly.
D)It is easily implemented on a recombining tree.
Question
Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.Compare this to a one-factor HJM model where   .Which of the following statements is most valid?</strong> A)ATMF bond option prices will be higher in the one-factor model. B)ATMF bond option prices will be lower in the one-factor model. C)ATMF bond option prices will be equal in the one- and two-factor models. D)There is insufficient information to determine the answer. <div style=padding-top: 35px> ,is given by the following binomial process with two shock terms: <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.Compare this to a one-factor HJM model where   .Which of the following statements is most valid?</strong> A)ATMF bond option prices will be higher in the one-factor model. B)ATMF bond option prices will be lower in the one-factor model. C)ATMF bond option prices will be equal in the one- and two-factor models. D)There is insufficient information to determine the answer. <div style=padding-top: 35px> ,where the forward rate movements are equiprobable.Compare this to a one-factor HJM model where <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.Compare this to a one-factor HJM model where   .Which of the following statements is most valid?</strong> A)ATMF bond option prices will be higher in the one-factor model. B)ATMF bond option prices will be lower in the one-factor model. C)ATMF bond option prices will be equal in the one- and two-factor models. D)There is insufficient information to determine the answer. <div style=padding-top: 35px> .Which of the following statements is most valid?
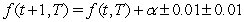
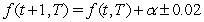
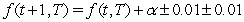
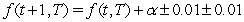
A)ATMF bond option prices will be higher in the one-factor model.
B)ATMF bond option prices will be lower in the one-factor model.
C)ATMF bond option prices will be equal in the one- and two-factor models.
D)There is insufficient information to determine the answer.
Question
Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a put option on a $100 notional,6.5% coupon bond,with a strike price of $100?</strong> A)0.25 B)0.54 C)0.77 D)0.96 <div style=padding-top: 35px> ,is given by the following binomial process with two shock terms: <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a put option on a $100 notional,6.5% coupon bond,with a strike price of $100?</strong> A)0.25 B)0.54 C)0.77 D)0.96 <div style=padding-top: 35px> ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a put option on a $100 notional,6.5% coupon bond,with a strike price of $100?

A)0.25
B)0.54
C)0.77
D)0.96
Question
The Libor Market Model is most often implemented by means of

A)A binomial tree.
B)A trinomial tree.
C)Monte Carlo simulation.
D)A closed-form approximation equation for derivative prices.
Question
Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a call option on a $100 notional,6.5% coupon bond,with a strike price of $100?</strong> A)0.25 B)0.31 C)0.43 D)0.55 <div style=padding-top: 35px> ,is given by the following binomial process with two shock terms: <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a call option on a $100 notional,6.5% coupon bond,with a strike price of $100?</strong> A)0.25 B)0.31 C)0.43 D)0.55 <div style=padding-top: 35px> ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a call option on a $100 notional,6.5% coupon bond,with a strike price of $100?

A)0.25
B)0.31
C)0.43
D)0.55
Unlock Deck
Sign up to unlock the cards in this deck!
Unlock Deck
Unlock Deck
1/20
auto play flashcards
Play
simple tutorial
Full screen (f)
exit full mode
Deck 28: The Heath-Jarrow-Morton Hjmand Libor Market Model LMM
1
Which of the following is not a valid property of the Heath-Jarrow-Morton (HJM)interest-rate framework?

A)The model may be calibrated to be consistent with any initial yield curve.
B)The tree version of the model has rates of all remaining maturities at each node of the tree.
C)The model fits volatilities of rates of all maturities.
D)The model is a one-factor model.
D
The HJM model is implementable for as many factors as desired.It is a very general framework that subsumes several other interest-rate models.
2
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  ,is given by the following binomial process: Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  ,where the up and down movements are equiprobable.What is the Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  value for Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)  ?
(a) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)
(b) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)
(c) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)
(d) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the   value for   ? (a)   (b)   (c)   (d)
D
The value of D The value of   in the up node will be   ,and in the down node will be   .The price of the two-year discount bond is   If we priced the same bond on the tree we would get   Equating the two pricing equations and re-arranging to solve for   we get  in the up node will be D The value of   in the up node will be   ,and in the down node will be   .The price of the two-year discount bond is   If we priced the same bond on the tree we would get   Equating the two pricing equations and re-arranging to solve for   we get  ,and in the down node will be D The value of   in the up node will be   ,and in the down node will be   .The price of the two-year discount bond is   If we priced the same bond on the tree we would get   Equating the two pricing equations and re-arranging to solve for   we get  .The price of the two-year discount bond is D The value of   in the up node will be   ,and in the down node will be   .The price of the two-year discount bond is   If we priced the same bond on the tree we would get   Equating the two pricing equations and re-arranging to solve for   we get  If we priced the same bond on the tree we would get D The value of   in the up node will be   ,and in the down node will be   .The price of the two-year discount bond is   If we priced the same bond on the tree we would get   Equating the two pricing equations and re-arranging to solve for   we get  Equating the two pricing equations and re-arranging to solve for D The value of   in the up node will be   ,and in the down node will be   .The price of the two-year discount bond is   If we priced the same bond on the tree we would get   Equating the two pricing equations and re-arranging to solve for   we get  we get D The value of   in the up node will be   ,and in the down node will be   .The price of the two-year discount bond is   If we priced the same bond on the tree we would get   Equating the two pricing equations and re-arranging to solve for   we get
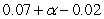
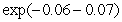
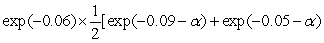
3
In the LMM,which of the following are martingales?

A)Libor rates.
B)Libor returns.
C)Zero-coupon rates.
D)Yields.
A
4
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)  ,is given by the following binomial process: Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)  ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be
(a) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)
(b) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)
(c) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)
(d) Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.Consider the price of one-year call and put options on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon.The difference between the call and put prices will be (a)   (b)   (c)   (d)
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
5
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year cap on the one-year forward rate at a strike rate of 7%.</strong> A)0.87 B)0.95 C)1.05 D)1.10 ,is given by the following binomial process: <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year cap on the one-year forward rate at a strike rate of 7%.</strong> A)0.87 B)0.95 C)1.05 D)1.10 ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year cap on the one-year forward rate at a strike rate of 7%.

A)0.87
B)0.95
C)1.05
D)1.10
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
6
Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  ,is given by the following binomial process with two shock terms: Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift ( Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  )for Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)  ?
(a) Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)
(b) Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)
(c) Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)
(d) Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the risk-neutral drift (   )for   ? (a)   (b)   (c)   (d)
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
7
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year floor on the one-year forward rate at a strike rate of 7%.</strong> A)0.85 B)0.89 C)0.95 D)1.00 ,is given by the following binomial process: <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year floor on the one-year forward rate at a strike rate of 7%.</strong> A)0.85 B)0.89 C)0.95 D)1.00 ,where the up and down movements are equiprobable.What is the price of a $100 notional one-year floor on the one-year forward rate at a strike rate of 7%.

A)0.85
B)0.89
C)0.95
D)1.00
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
8
Swap rates in the SMM are,under the risk-neutral forward measure

A)Normal.
B)Lognormal.
C)Exponential.
D)None of the above.
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
9
The HJM model is implemented by depicting the evolution of which rates in particular?

A)Yields.
B)Zero-coupon rates.
C)Forward rates.
D)Discount functions.
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
10
Which of the following is not necessarily a beneficial feature of the HJM binomial tree class of models?

A)The drift term is obtained in analytical form as a function of the volatilities.
B)The binomial tree carries the entire term structure of forward rates at each node.
C)The tree is recombining because the drift terms are available in analytical form.
D)The approach requires only drawing the tree out to the maturity of the option,and not to the maturity of bonds underlying a bond option.
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
11
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a one-year put option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?</strong> A)1.00 B)1.26 C)1.54 D)1.67 ,is given by the following binomial process: <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a one-year put option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?</strong> A)1.00 B)1.26 C)1.54 D)1.67 ,where the up and down movements are equiprobable.What is the price of a one-year put option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?

A)1.00
B)1.26
C)1.54
D)1.67
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
12
Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  .Each Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  -th forward rate has constant volatility Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  .For each forward period of one year what is the risk-neutral drift term in the Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)  -th period equal to?
(a) Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)
(b) Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)
(c) Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)
(d) Consider a one-factor HJM model on a binomial model with time steps of one year and a probability of an up shift of   .Each   -th forward rate has constant volatility   .For each forward period of one year what is the risk-neutral drift term in the   -th period equal to? (a)   (b)   (c)   (d)
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
13
The numeraire in the Swap Market Model (SMM)is

A)The price of the longest maturity bond (i.e. ,the numeraire under forward measure).
B)The total of discount functions to the longest swap maturity.
C)The money market account.
D)The value of the fixed side of the swap.
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
14
Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a one-year call option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?</strong> A)0.50 B)0.55 C)0.60 D)0.65 ,is given by the following binomial process: <strong>Consider a one-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process:   ,where the up and down movements are equiprobable.What is the price of a one-year call option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?</strong> A)0.50 B)0.55 C)0.60 D)0.65 ,where the up and down movements are equiprobable.What is the price of a one-year call option on a two-year 6.5% coupon bond,with a strike price of $100 ex-coupon?

A)0.50
B)0.55
C)0.60
D)0.65
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
15
In the HJM model,one of the striking features is that the risk-neutral drifts in the model are functions of only the

A)The forward rates.
B)The yields.
C)The volatility of forward rates.
D)The risk premia for interest-rate risk.
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
16
In the Libor Market Model (LMM)which of the following is not a beneficial feature of the model?

A)The LMM only requires one factor for each rate.
B)The model is easily calibrated to the Black model caplet/floorlet prices.
C)The evolution of Libor rates is modeled directly.
D)It is easily implemented on a recombining tree.
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
17
Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.Compare this to a one-factor HJM model where   .Which of the following statements is most valid?</strong> A)ATMF bond option prices will be higher in the one-factor model. B)ATMF bond option prices will be lower in the one-factor model. C)ATMF bond option prices will be equal in the one- and two-factor models. D)There is insufficient information to determine the answer. ,is given by the following binomial process with two shock terms: <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.Compare this to a one-factor HJM model where   .Which of the following statements is most valid?</strong> A)ATMF bond option prices will be higher in the one-factor model. B)ATMF bond option prices will be lower in the one-factor model. C)ATMF bond option prices will be equal in the one- and two-factor models. D)There is insufficient information to determine the answer. ,where the forward rate movements are equiprobable.Compare this to a one-factor HJM model where <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.Compare this to a one-factor HJM model where   .Which of the following statements is most valid?</strong> A)ATMF bond option prices will be higher in the one-factor model. B)ATMF bond option prices will be lower in the one-factor model. C)ATMF bond option prices will be equal in the one- and two-factor models. D)There is insufficient information to determine the answer. .Which of the following statements is most valid?

A)ATMF bond option prices will be higher in the one-factor model.
B)ATMF bond option prices will be lower in the one-factor model.
C)ATMF bond option prices will be equal in the one- and two-factor models.
D)There is insufficient information to determine the answer.
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
18
Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a put option on a $100 notional,6.5% coupon bond,with a strike price of $100?</strong> A)0.25 B)0.54 C)0.77 D)0.96 ,is given by the following binomial process with two shock terms: <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a put option on a $100 notional,6.5% coupon bond,with a strike price of $100?</strong> A)0.25 B)0.54 C)0.77 D)0.96 ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a put option on a $100 notional,6.5% coupon bond,with a strike price of $100?

A)0.25
B)0.54
C)0.77
D)0.96
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
19
The Libor Market Model is most often implemented by means of

A)A binomial tree.
B)A trinomial tree.
C)Monte Carlo simulation.
D)A closed-form approximation equation for derivative prices.
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
20
Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a call option on a $100 notional,6.5% coupon bond,with a strike price of $100?</strong> A)0.25 B)0.31 C)0.43 D)0.55 ,is given by the following binomial process with two shock terms: <strong>Consider a two-factor HJM model where the initial forward curve is given as 6% for one year and 7% between one and two years.The evolution of continuously-compounded one-year forward rates beginning at time   ,is given by the following binomial process with two shock terms:   ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a call option on a $100 notional,6.5% coupon bond,with a strike price of $100?</strong> A)0.25 B)0.31 C)0.43 D)0.55 ,where the forward rate movements are equiprobable.What this means is that the forward rate may move up by either 0.02 with probability 1/4,or move down by 0.02 with probability 1/4,or remain the same with probability 1/2.What is the price of a call option on a $100 notional,6.5% coupon bond,with a strike price of $100?

A)0.25
B)0.31
C)0.43
D)0.55
Unlock Deck
Unlock for access to all 20 flashcards in this deck.
Unlock Deck
k this deck
locked card icon
Unlock Deck
Unlock for access to all 20 flashcards in this deck.