Multiple Choice
Assume that Jones Co. will need to purchase 100,000 Singapore dollars (S$) in 180 days. Today's spot rate of the S$ is $.50, and the 180-day forward rate is $.53. A call option on S$ exists, with an exercise price of $.52, a premium of $.02, and a 180-day expiration date. A put option on S$ exists, with an exercise price of $.51, a premium of $.02, and a 180-day expiration date. Jones has developed the following probability distribution for the spot rate in 180 days: 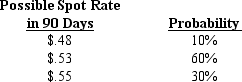 The probability that the forward hedge will result in a higher payment than the options hedge is ____ (include the amount paid for the premium when estimating the U.S. dollars required for the options hedge) .
A) 0%
B) 10%
C) 30%
D) 40%
E) 70%
Correct Answer:

Verified
Correct Answer:
Verified
Q13: An advantage of using options to hedge
Q19: Exhibit 11-1<br> <img src="https://d2lvgg3v3hfg70.cloudfront.net/TB2125/.jpg" alt="Exhibit 11-1
Q26: When a perfect hedge is not available
Q44: If Lazer Co. desired to lock in
Q46: MNCs generally do not need to hedge
Q47: Lorre Company needs 200,000 Canadian dollars (C$)
Q47: Lagging refers to the delay of payment
Q50: Use the following information to calculate the
Q53: Spears Co. will receive SF1,000,000 in 30
Q87: To hedge a payable position with a