Multiple Choice
On 1 July20X0, Abel Ltd entered into a 50:50 joint operation with Tasman Ltd to develop an oil field off the south coast of Tasmania. Each operator's initial contribution was $2 million. Abel contributed $1 million cash and equipment with a fair value of $1 million and a book value of $500 000. Tasman's contributed $2 million cash.
Additional information
Production costs for the JO for the year ended 30 June 20X1 were: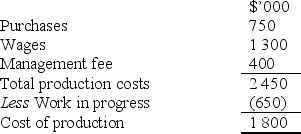
The remaining useful life of the equipment contributed by Abel is 5 years.
Tasman is responsible for the day to day management of JO and has recognised the management fee received during the year as revenue. The costs of providing these management services to JO was $225 000.
Tasman has sold all of the oil distributed to it and Abel has sold 50% of the oil distributed to it by 30 June 20X1.
An extract of JO's balance sheet at 30 June 20X1 shows: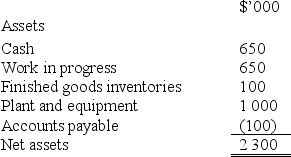
Which of the following will not form part of Abel Ltd's initial contribution entry?
A) Debit against the cash in JO account of $1 500 000.
B) Debit against the equipment in JO account of $500 000.
C) Credit against the cash of $1 000 000.
D) Credit against the gain on equipment of $250 000.
Correct Answer:

Verified
Correct Answer:
Verified
Q2: The particular relationship between parties that signifies
Q8: Which of the following statements is not
Q17: Wiseye Limited and Goodbody Limited agreed to
Q18: A 50:50 joint operation was commenced between
Q19: When a joint operator is accounting for
Q20: Company A Limited and Company B Limited
Q21: On 1 July 20X0, Abel Ltd entered
Q22: Which of the following statements is not
Q24: Cash contributed to a joint operation was
Q26: A 50:50 joint operation was commenced between