Multiple Choice
You want to evaluate three mutual funds using the Sharpe measure for performance evaluation. The risk-free return during the sample period is 5%. The average returns, standard deviations, and betas for the three funds are given below, as are the data for the S&P 500 Index.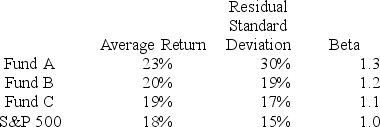
The investment with the highest Sharpe measure is
A) Fund A.
B) Fund B.
C) Fund C.
D) the index.
E) Funds A and C (tied for highest) .
Correct Answer:

Verified
Correct Answer:
Verified
Q15: The following data are available relating to
Q17: You want to evaluate three mutual funds
Q20: In a particular year, Razorback Mutual Fund
Q21: The following data are available relating to
Q22: In a particular year, Razorback Mutual Fund
Q23: The M2 measure was developed by<br>A) Merton
Q27: Suppose you purchase one share of the
Q38: Mutual funds show _ evidence of serial
Q52: Suppose you purchase 100 shares of GM
Q56: Hedge funds I) are appropriate as a