Multiple Choice
USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Consider the following information for four portfolios, the market, and the risk-free rate (RFR) :
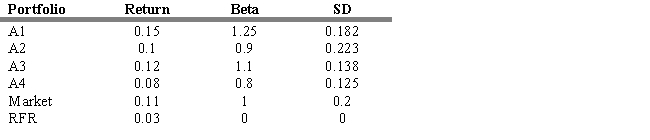
-Refer to Exhibit 18.6. Calculate the Treynor Measure for each portfolio.
A) A1 = 0.0625, A2 = 0.0778, A3 = 0.0818, A4 = 0.096
B) A1 = 0.096, A2 = 0.0778, A3 = 0.0818, A4 = 0.0625
C) A1 = 0.096, A2 = 0.0818, A3 = 0.0778, A4 = 0.0625
D) A1 = 0.0778, A2 = 0.096, A3 = 0.0818, A4 = 0.0625
E) A1 = 0.086, A2 = 0.096, A3 = 0.0818, A4 = 0.0625
Correct Answer:

Verified
Correct Answer:
Verified
Q92: Attribution analysis separates a portfolio manager's performance
Q93: Money-weighted returns set the present value of
Q94: Funds with low levels of diversification tend
Q95: Portfolio managers are often evaluated using a
Q96: Selectivity measures how well a portfolio performed
Q98: Treynor showed that rational, risk-averse investors always
Q99: A peer group comparison collects the returns
Q100: The major requirements of a portfolio manager
Q101: Relative return portfolio performance measures<br>A) adjust portfolio
Q102: The Sortino ratio takes into account the