Solved

Carter Ltd

Question 43

Essay

Carter Ltd. is considering purchasing a new machine which will increase its current capacity of 100,000 units by 20%. The new machine, which will be acquired on January 1 of year 1 costs $4,000,000. Carter will also incur installation costs of $400,000 which are eligible for capital cost allowance. The new machine will have a useful life of 5 years and an estimated residual value of $200,000. The current machine has an undepreciated capital cost equal to its salvage value as at January 1, year 1 of $200,000. Annual depreciation of $45,000 calculated on a straight line basis is being recorded. The applicable capital cost allowance rate for both machines is 30%.
Budgeted unit cost data for Year 1 assuming an activity level of 90,000 units are as follows:
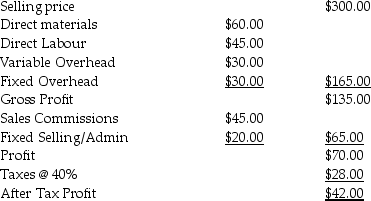
Carter Ltd. is considering purchasing a new machine which will increase its current capacity of 100,000 units by 20%. The new machine, which will be acquired on January 1 of year 1 costs $4,000,000. Carter will also incur installation costs of $400,000 which are eligible for capital cost allowance. The new machine will have a useful life of 5 years and an estimated residual value of $200,000. The current machine has an undepreciated capital cost equal to its salvage value as at January 1, year 1 of $200,000. Annual depreciation of $45,000 calculated on a straight line basis is being recorded. The applicable capital cost allowance rate for both machines is 30%. Budgeted unit cost data for Year 1 assuming an activity level of 90,000 units are as follows:    Additional information is as follows: • Sales commissions are 15% of sales. • Variable and fixed manufacturing overheads are applied on the basis of machine hours. • The new machine is expected to reduce direct materials costs by 5% and direct labour costs by 20% • It is estimated unit sales will increase by 3,000 units/year for years 1 to 5 inclusive. • Inflation on selling prices and variable costs is predicted at 8%/year.    • If the old machine is not replaced it will require maintenance expenses of $50,000 in year 2 and another $30,000 in the year 4. • The company requires a real return of 11% • The asset will be sold before year end of year 5 and therefore will not be eligible for CCA in year 5. Required: Should the new machine be purchased? Additional information is as follows:
• Sales commissions are 15% of sales.
• Variable and fixed manufacturing overheads are applied on the basis of machine hours.
• The new machine is expected to reduce direct materials costs by 5% and direct labour costs by 20%
• It is estimated unit sales will increase by 3,000 units/year for years 1 to 5 inclusive.
• Inflation on selling prices and variable costs is predicted at 8%/year.
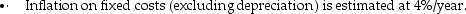
Carter Ltd. is considering purchasing a new machine which will increase its current capacity of 100,000 units by 20%. The new machine, which will be acquired on January 1 of year 1 costs $4,000,000. Carter will also incur installation costs of $400,000 which are eligible for capital cost allowance. The new machine will have a useful life of 5 years and an estimated residual value of $200,000. The current machine has an undepreciated capital cost equal to its salvage value as at January 1, year 1 of $200,000. Annual depreciation of $45,000 calculated on a straight line basis is being recorded. The applicable capital cost allowance rate for both machines is 30%. Budgeted unit cost data for Year 1 assuming an activity level of 90,000 units are as follows:    Additional information is as follows: • Sales commissions are 15% of sales. • Variable and fixed manufacturing overheads are applied on the basis of machine hours. • The new machine is expected to reduce direct materials costs by 5% and direct labour costs by 20% • It is estimated unit sales will increase by 3,000 units/year for years 1 to 5 inclusive. • Inflation on selling prices and variable costs is predicted at 8%/year.    • If the old machine is not replaced it will require maintenance expenses of $50,000 in year 2 and another $30,000 in the year 4. • The company requires a real return of 11% • The asset will be sold before year end of year 5 and therefore will not be eligible for CCA in year 5. Required: Should the new machine be purchased? • If the old machine is not replaced it will require maintenance expenses of $50,000 in year 2 and another $30,000 in the year 4.
• The company requires a real return of 11%
• The asset will be sold before year end of year 5 and therefore will not be eligible for CCA in year 5.
Required:
Should the new machine be purchased?

Correct Answer:

verifed

Verified

Note the nominal discount rate = 1 - (1+...

View Answer

Unlock this answer now
Get Access to more Verified Answers free of charge

Related Questions