Multiple Choice
Will an arbitrageur facing the following prices be able to make money? 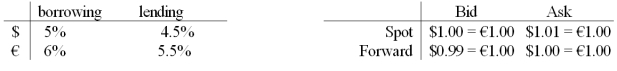
A) Yes, borrow $1,000 at 5%; Trade for € at the ask spot rate $1.01 = €1.00; Invest €990.10 at 5.5%; Hedge this with a forward contract on €1,044.55 at $0.99 = €1.00; Receive $1.034.11.
B) Yes, borrow €1,000 at 6%; Trade for $ at the bid spot rate $1.00 = €1.00; Invest $1,000 at 4.5%; Hedge this with a forward contract on €1,045 at $1.00 = €1.00.
C) No; the transactions costs are too high.
D) None of the above
Correct Answer:

Verified
Correct Answer:
Verified
Q10: According to the monetary approach,the exchange
Q12: A formal statement of IRP is<br>A)
Q30: The moving average crossover rule<br>A)is a fundamental
Q61: If you borrowed €1,000,000 for one year,
Q61: If you borrowed €1,000,000 for one year,
Q61: If you borrowed €1,000,000 for one year,
Q67: There is (at least) one (smallish) profitable
Q73: When Interest Rate Parity (IRP) does not
Q74: USING YOUR PREVIOUS ANSWERS and a bit
Q97: USING YOUR PREVIOUS ANSWERS and a bit