Multiple Choice
Suppose a U.S.firm has an asset in Britain whose local currency price is random.For simplicity,suppose there are only three states of the world and each state is equally likely to occur.The future local currency price of this British asset (P*) as well as the future exchange rate (S) will be determined,depending on the realized state of the world. 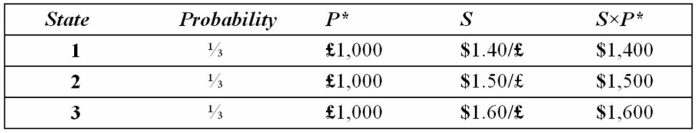 Which of the following statements is most correct?
A) The firm faces no exchange rate risk since the local currency price of the asset and the exchange rate are negatively correlated.
B) The firm faces substantial exchange rate risk since the local currency price of the asset and the exchange rate are positively correlated.
C) The firm's exchange rate exposure can be completely hedged with derivatives written on the British pound.
D) Since randomness is involved, no hedging is possible.
Correct Answer:

Verified
Correct Answer:
Verified
Q21: Which of the following is false?<br>A)The competitive
Q35: Two studies found a link between exchange
Q38: The "exposure" (i.e.the regression coefficient beta)is: Hint:
Q41: The "exposure" (i.e.the regression coefficient beta)is: Hint:
Q47: Suppose a U.S.firm has an asset in
Q47: If the stock market of a foreign
Q49: The firm may not be able to
Q71: A U.S. firm holds an asset in
Q73: The price elasticity of demand for unique
Q85: Consider a U.S.-based MNC with a wholly-owned