Solved

Consider the Following Discrete Probability Distributions of Payoffs for 3

Question 51

Multiple Choice

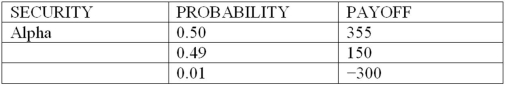
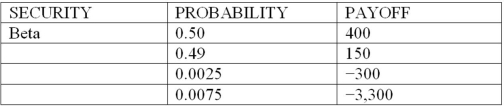
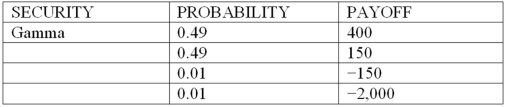
Consider the following discrete probability distributions of payoffs for 3 securities that are held in a DI's trading portfolio (payoff amounts shown are in $millions) : Consider the following discrete probability distributions of payoffs for 3 securities that are held in a DI's trading portfolio (payoff amounts shown are in $millions) :       What is the expected payoff, the 99% value at risk (VAR)  and the expected shortfall (ES)  of security Gamma (in millions) ? A) +$248; -$2,000; -$2000 B) -$248; -$20; -$2,000 C) -$2.150; -$2,150; -$2,150 D) +$248; -$21.50; -$20.00 E) ±$0.00; -248; -$2,150 Consider the following discrete probability distributions of payoffs for 3 securities that are held in a DI's trading portfolio (payoff amounts shown are in $millions) :       What is the expected payoff, the 99% value at risk (VAR)  and the expected shortfall (ES)  of security Gamma (in millions) ? A) +$248; -$2,000; -$2000 B) -$248; -$20; -$2,000 C) -$2.150; -$2,150; -$2,150 D) +$248; -$21.50; -$20.00 E) ±$0.00; -248; -$2,150 Consider the following discrete probability distributions of payoffs for 3 securities that are held in a DI's trading portfolio (payoff amounts shown are in $millions) :       What is the expected payoff, the 99% value at risk (VAR)  and the expected shortfall (ES)  of security Gamma (in millions) ? A) +$248; -$2,000; -$2000 B) -$248; -$20; -$2,000 C) -$2.150; -$2,150; -$2,150 D) +$248; -$21.50; -$20.00 E) ±$0.00; -248; -$2,150 What is the expected payoff, the 99% value at risk (VAR) and the expected shortfall (ES) of security Gamma (in millions) ?

A) +$248; -$2,000; -$2000
B) -$248; -$20; -$2,000
C) -$2.150; -$2,150; -$2,150
D) +$248; -$21.50; -$20.00
E) ±$0.00; -248; -$2,150

Correct Answer:

verifed

Verified

Unlock this answer now
Get Access to more Verified Answers free of charge

Related Questions