Multiple Choice
Consider the following discrete probability distributions of payoffs for 3 securities that are held in a DI's trading portfolio (payoff amounts shown are in $millions) : 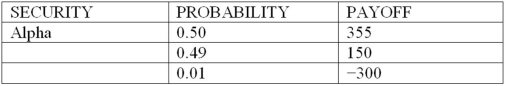
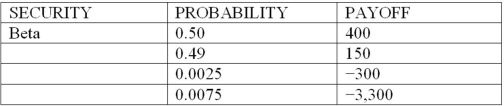
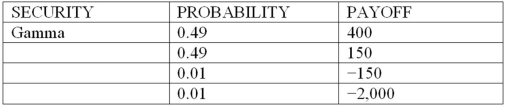 What are the expected returns for securities Alpha and Beta, respectively (in millions) ?
A) -$248 and + 248
B) +$248 and +$248
C) -$300 and +$400
D) +$300 and - $3,300
E) none of these
Correct Answer:

Verified
Correct Answer:
Verified
Q2: Calculating the risk of a multi-asset trading
Q7: The RiskMetrics model generally prefers using the
Q11: Assets and liabilities that are expected to
Q46: If a trader in charge of an
Q53: An advantage of the historic or back
Q54: Consider the following discrete probability distributions of
Q57: Which approach to measuring market risk, in
Q59: Sumitomo Bank's risk manager has estimated that
Q60: The use of expected shortfall (ES) is
Q62: The VaR of a bank's trading portfolio