Multiple Choice
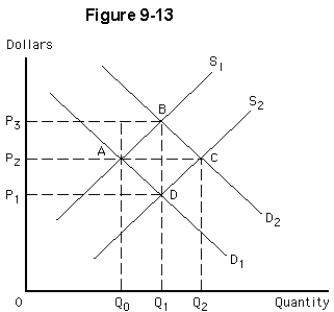
-Assume the initial equilibrium is at point D in Figure 9-13.If the market demand curve shifts from D₁ to D₂,and this results in entry of new firms in the long-run,the new equilibrium in this increasing-cost industry will be
A) both C and E
B) both D and E
C) at a price less than P₁
D) at a price higher than P₁
E) at an output greater than Q₁
Correct Answer:

Verified
Correct Answer:
Verified
Q158: A firm suffers an economic loss whenever<br>A)price
Q159: In perfect competition,<br>A)there are typically two or
Q160: In the short run,<br>A)new firms may enter
Q161: The portion of the marginal cost curve
Q162: A perfectly competitive firm may earn economic
Q164: The long-run market supply curve in a
Q165: <img src="https://d2lvgg3v3hfg70.cloudfront.net/TB3973/.jpg" alt=" -In short-run equilibrium,the
Q166: A firm in a perfectly competitive market
Q167: <img src="https://d2lvgg3v3hfg70.cloudfront.net/TB3973/.jpg" alt=" -The All-the-Rage microbrewery
Q168: A perfectly competitive firm<br>A)can increase total revenue