Multiple Choice
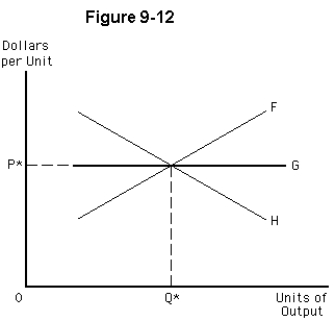
-Figure 9-12 shows three possible long-run supply curves for an industry that is currently in equilibrium with price (P*) and quantity (Q*) .Which of the following statements is correct?
A) The long-run supply curve would be F for a decreasing-cost industry,H for an increasing-cost industry,and G for a constant-cost industry.
B) All three long-run supply curves indicate that the firms' LRATC curves shift as industry output expands.
C) If the industry uses a significant portion of a scarce input,the long-run supply curve would likely be curve H.
D) An industry that moves along long-run supply curve F earns above-normal profits in the long run.
E) If an increase in market output leads to lower prices for a key input,the long-run supply curve would likely be curve H.
Correct Answer:

Verified
Correct Answer:
Verified
Q114: Which of the following is not a
Q115: <img src="https://d2lvgg3v3hfg70.cloudfront.net/TB3973/.jpg" alt=" -In short-run equilibrium,the
Q116: In a perfectly competitive market,transient economic profit
Q117: <img src="https://d2lvgg3v3hfg70.cloudfront.net/TB3973/.jpg" alt=" -Figure 9-2 shows
Q118: Which of the following is true of
Q120: In perfect competition<br>A)the demand curve facing the
Q121: In a decreasing-cost industry,the long-run industry supply
Q122: <img src="https://d2lvgg3v3hfg70.cloudfront.net/TB3973/.jpg" alt=" -Figure 9-1 shows
Q123: In a perfectly competitive market,the good or
Q124: <img src="https://d2lvgg3v3hfg70.cloudfront.net/TB3973/.jpg" alt=" -Figure 9-2 shows