Multiple Choice
Lorre Co. needs 200,000 Canadian dollars (C$) in 90 days and is trying to determine whether or not to hedge this position. Lorre has developed the following probability distribution for the Canadian dollar: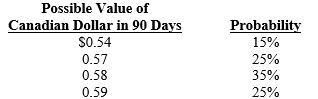
The 90-day forward rate of the Canadian dollar is $.575, and the expected spot rate of the Canadian dollar in 90 days is $.55. If Lorre implements a forward hedge, what is the probability that hedging will be more costly to the firm than not hedging?
A) 40 percent
B) 60 percent
C) 15 percent
D) 85 percent
Correct Answer:

Verified
Correct Answer:
Verified
Q3: When comparing the forward hedge to the
Q8: Blake Inc. needs €1,000,000 in 30 days.
Q9: If interest rate parity exists, the forward
Q10: Which of the following might be used
Q14: Assume that Smith Corp. will need to
Q18: Samson Inc. needs €1,000,000 in 30 days.
Q46: A money market hedge on payables would
Q49: A futures hedge involves taking a money
Q57: The _ hedge is not a technique
Q65: A _ does not represent an obligation.<br>A)