Multiple Choice
BVC began operations January 1, 20x1.Financial statements for the year ended December 31, 20x1, and 20x2, contained the following errors: 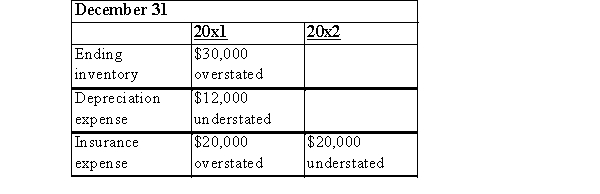 In addition, on December 26, 20x2, fully depreciated machinery was sold for $21,600 cash, but the sale was not recorded until 20x3. There were no other errors during 20x1 or 20x2, and no corrections have been made for any of the errors.
What is the total pre-tax effect of the errors on 20x2 net income?
A) $71,600 Overstated
B) $50,000 Overstated
C) $53,600 Overstated
D) $28,400 Overstated
Correct Answer:

Verified
Correct Answer:
Verified
Q16: Change in accounting estimate requires that a
Q17: In 20x2, a firm changed from the
Q18: A company has been using straight-line depreciation
Q19: An increase in assets relating to a
Q20: Depreciation expense for the most recent fiscal
Q22: A change from inventory costing using FIFO
Q23: Most changes in accounting principle are recognized
Q24: On comparative financial statements, all errors must
Q25: The concept of consistency is sacrificed in
Q26: The ending inventory of XZW was overstated