Multiple Choice
Exhibit 8-18 A typical firm in a perfectly competitive market 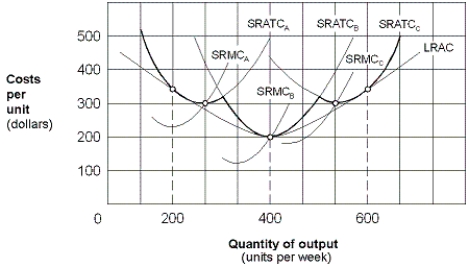
-In Exhibit 8-18, assume the perfectly competitive firm is in long-run equilibrium and there is an increase in demand. As a result, the firm in the short run will increase output along its:
A) short-run average total cost curve B.
B) short-run marginal cost curve B.
C) long-run average cost curve.
D) none of these because the firm shuts down.
Correct Answer:

Verified
Correct Answer:
Verified
Q37: In the perfectly competitive market, all firms
Q39: Assume a competitive market has firms earning
Q126: Above the shutdown point, a competitive firm's
Q204: If a firm increases output when MR
Q206: Exhibit 8-18 A typical firm in a
Q207: Assume that a firm's marginal revenue just
Q210: Suppose product price is fixed at $24;
Q211: The neighborhood ice cream shop finds that
Q212: A perfectly competitive firm's short-run supply curve
Q214: When the price of a good is