Multiple Choice
Martin operates a law practice as a sole proprietorship using the cash method of accounting. Martin incorporates the law practice and transfers the following items to a new, solely owned corporation. 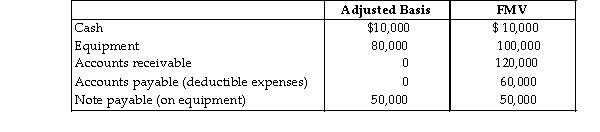 Martin must recognize a gain of and has a stock basis of :
A) $20,000; $40,000
B) $20,000; $30,000
C) $0; $40,000
D) $0; $30,000
Correct Answer:

Verified
Correct Answer:
Verified
Q14: Identify which of the following statements is
Q19: Any losses on the sale of Section
Q22: In 2017, Phoenix Corporation is a controlled
Q43: Why would a transferor want to avoid
Q46: Dan transfers property with an adjusted basis
Q61: Beth transfers an asset having an FMV
Q65: Nonresident aliens are not allowed to claim
Q100: Jeremy operates a business as a sole
Q106: Lynn transfers property with a $56,000 adjusted
Q120: Barry, Dan, and Edith together form a