Multiple Choice
Refer to the graph shown, which depicts a perfectly competitive firm. When the industry is in long-run competitive equilibrium: 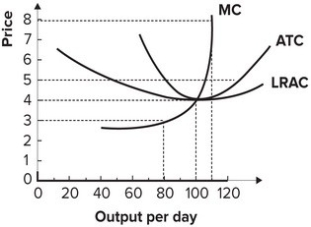
A) the price of the product will be $6.
B) the firm will produce 100 units of output.
C) the firm will earn economic profits of $300 per day.
D) the marginal cost of production will be $3.
Correct Answer:

Verified
Correct Answer:
Verified
Q28: Refer to the graph shown. If market
Q29: If the marginal revenue of the next
Q30: If long-run average total cost exceeds marginal
Q31: Refer to the graph shown. What level
Q32: To maximize profits, a perfectly competitive firm
Q34: Refer to the graph shown. Suppose the
Q35: Total profit is maximized at the output
Q36: Refer to the graph shown. A perfectly
Q37: Refer to the graphs shown, which depict
Q38: The demand curve for a firm in