Multiple Choice
Martin operates a law practice as a sole proprietorship using the cash method of accounting. Martin incorporates the law practice and transfers the following items to a new, solely owned corporation. 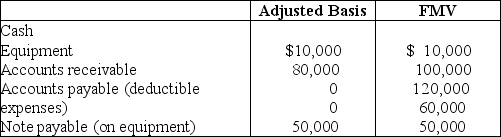 Martin must recognize a gain of ________ and has a stock basis of ________:
A) $0; $30,000
B) $0; $40,000
C) $20,000; $30,000
D) $20,000; $40,000
Correct Answer:

Verified
Correct Answer:
Verified
Q26: Which of the following statements is incorrect?<br>A)S
Q27: Section 351 applies to an exchange if
Q32: Identify which of the following statements is
Q53: Michael contributes equipment with a $25,000 adjusted
Q58: Carolyn transfers property with an adjusted basis
Q63: Sarah transfers property with an $80,000 adjusted
Q80: Lynn transfers land having a $50,000 adjusted
Q91: Abby owns all 100 shares of Rent
Q98: Lynn transfers property with a $56,000 adjusted
Q121: Colleen operates a business as a sole