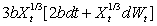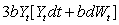Deck 15: Mathematics of Black-Scholes

Full screen (f)
exit full mode
Question
The Black-Scholes model is based on a posited stochastic process for stock prices,where the movements in the stock are represented mathematically by a stochastic differential equation (SDE).Which of the following statements is most valid?

A)The SDE is a differential equation that changes over time.
B)The solution to the SDE is a random function of time.
C)The solution to the SDE is a deterministic function of time.
D)The solution to the SDE is the Black-Scholes formula.
Use Space or
up arrow
down arrow
to flip the card.
Question
Consider a stock that is trading at $50,has a volatility of 0.5,and pays no dividends.The risk-free rate is 4%.If the beta of the stock is 1.1,what is the beta of a 52-strike,one-year call option on this stock?

A)0.55
B)1.1
C)3.3
D)4.4
Question
Given that Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)  <div style=padding-top: 35px> and Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)  <div style=padding-top: 35px> ,what is Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)  <div style=padding-top: 35px> ?
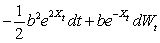
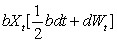
(a) Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)  <div style=padding-top: 35px>
(b) Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)  <div style=padding-top: 35px>
(c) Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)  <div style=padding-top: 35px>
)
(d) Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)  <div style=padding-top: 35px>
Question
Which of the following is not a characteristic of a price process Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.<div style=padding-top: 35px> that follows a geometric Brownian motion (GBM)?
(a) Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.<div style=padding-top: 35px>
Is an exponential function of a linear Ito process
Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.<div style=padding-top: 35px>
,where
Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.<div style=padding-top: 35px>
And
Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.<div style=padding-top: 35px>
Are constants.
(b) Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.<div style=padding-top: 35px>
Is normally distributed.
(c) Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.<div style=padding-top: 35px>
Is a continuous process,i.e. ,there are no market "gaps."
(d) Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.<div style=padding-top: 35px>
Is non-negative.
Question
Given that Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> and Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ,what is Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ?
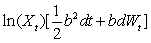
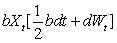
(a) Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(b) Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(c) Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(d) Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
Question
A call option in the Black-Scholes model is a function of the stock price and time,i.e. , <strong>A call option in the Black-Scholes model is a function of the stock price and time,i.e. ,   .Which of the following statements is valid with regards to the change in the option price over time,i.e. ,   ?</strong> A)The expected change   Is not a function of stock volatility-taking expectations eliminates the Wiener process term. B)The expected change over time is not a function of the remaining maturity of the option,only of the amount of time over which the change is examined. C)The expected change in the call price is not a function of the risk-free interest rate but only the growth rate of the stock at the specific point in time. D)None of the above. <div style=padding-top: 35px> .Which of the following statements is valid with regards to the change in the option price over time,i.e. , <strong>A call option in the Black-Scholes model is a function of the stock price and time,i.e. ,   .Which of the following statements is valid with regards to the change in the option price over time,i.e. ,   ?</strong> A)The expected change   Is not a function of stock volatility-taking expectations eliminates the Wiener process term. B)The expected change over time is not a function of the remaining maturity of the option,only of the amount of time over which the change is examined. C)The expected change in the call price is not a function of the risk-free interest rate but only the growth rate of the stock at the specific point in time. D)None of the above. <div style=padding-top: 35px> ?

A)The expected change <strong>A call option in the Black-Scholes model is a function of the stock price and time,i.e. ,   .Which of the following statements is valid with regards to the change in the option price over time,i.e. ,   ?</strong> A)The expected change   Is not a function of stock volatility-taking expectations eliminates the Wiener process term. B)The expected change over time is not a function of the remaining maturity of the option,only of the amount of time over which the change is examined. C)The expected change in the call price is not a function of the risk-free interest rate but only the growth rate of the stock at the specific point in time. D)None of the above. <div style=padding-top: 35px>
Is not a function of stock volatility-taking expectations eliminates the Wiener process term.
B)The expected change over time is not a function of the remaining maturity of the option,only of the amount of time over which the change is examined.
C)The expected change in the call price is not a function of the risk-free interest rate but only the growth rate of the stock at the specific point in time.
D)None of the above.
Question
Which of the following is necessary in order to solve the fundamental PDE to obtain the price of a derivative security?

A)The utility function of the representative investor trading in that derivative security.
B)The growth rate of the price of the derivative security.
C)The boundary conditions for the payoffs of the security.
D)A benchmark price of a related derivative security that is correlated with the security being priced.
Question
The fundamental asset pricing partial differential equation (PDE)is used to derive the Black-Scholes formula.Which of the following statements is not true about the fundamental PDE?

A)The PDE depends on the growth rate of the stock.
B)The PDE is independent of the the utility function of the investor buying the option.
C)The PDE is the same for both calls and puts,the only difference being in the boundary conditions.
D)The solution to the PDE is the Black-Scholes option pricing formula.
Question
Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of   .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put?
(a) Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of   .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(b) Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of   .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(c) Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of   .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(d) Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of   .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
Question
Which of the following properties of a put option's beta is most valid?

A)The beta of a put increases as the stock price increases.
B)The beta of a put decreases if the beta of the stock increases.
C)The beta of a put is bounded between <strong>Which of the following properties of a put option's beta is most valid?</strong> A)The beta of a put increases as the stock price increases. B)The beta of a put decreases if the beta of the stock increases. C)The beta of a put is bounded between   ) D)The beta is always positive. <div style=padding-top: 35px>
)
D)The beta is always positive.
Question
Given the following Ito process for a stock: <strong>Given the following Ito process for a stock:   ,what is the expected value of the stock after 3 years if the current price of the stock is $50?</strong> A)$71.67 B)$86.40 C)$91.11 D)$115.82 <div style=padding-top: 35px> ,what is the expected value of the stock after 3 years if the current price of the stock is $50?
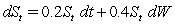
A)$71.67
B)$86.40
C)$91.11
D)$115.82
Question
Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process <strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero. <div style=padding-top: 35px> ,given <strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero. <div style=padding-top: 35px> ?

A)The process has independent increments <strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero. <div style=padding-top: 35px>
,for
<strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero. <div style=padding-top: 35px>
)
B)Increments are normally distributed.
C)For each <strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero. <div style=padding-top: 35px>
,
<strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero. <div style=padding-top: 35px>
Is normally distributed with mean zero and variance
<strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero. <div style=padding-top: 35px>
)
D)The process <strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero. <div style=padding-top: 35px>
Is a symmetric random walk around zero.
Question
Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes <strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. <div style=padding-top: 35px> are

A)A special case of Wiener processes <strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. <div style=padding-top: 35px>
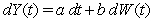
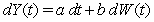
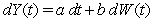
)
B)Are functions of Wiener processes: in SDE form, <strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. <div style=padding-top: 35px>
)
C)Are functions of Wiener processes: in SDE form, <strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. <div style=padding-top: 35px>
,with the restriction that
<strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. <div style=padding-top: 35px>
And
<strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. <div style=padding-top: 35px>
Have to be constants.
D)Are functions of Wiener processes: in SDE form, <strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. <div style=padding-top: 35px>
,with the restriction that
<strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. <div style=padding-top: 35px>
And
<strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. <div style=padding-top: 35px>
Have to be constants or functions of time
<strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. <div style=padding-top: 35px>
Alone.
Question
Given that Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> and Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ,what is Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px> ?
(a) Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(b) Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(c) Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
(d) Given that   and   ,what is   ? (a)   (b)   (c)   (d)  <div style=padding-top: 35px>
Question
Consider a stock that is trading at $50.A six-month at-the-money call option on the stock has a price of 3.45 and a delta of 0.60.The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the call?

A)0.66
B)1.1
C)9.56
D)15.94
Unlock Deck
Sign up to unlock the cards in this deck!
Unlock Deck
Unlock Deck
1/15
auto play flashcards
Play
simple tutorial
Full screen (f)
exit full mode
Deck 15: Mathematics of Black-Scholes
1
The Black-Scholes model is based on a posited stochastic process for stock prices,where the movements in the stock are represented mathematically by a stochastic differential equation (SDE).Which of the following statements is most valid?

A)The SDE is a differential equation that changes over time.
B)The solution to the SDE is a random function of time.
C)The solution to the SDE is a deterministic function of time.
D)The solution to the SDE is the Black-Scholes formula.
B
The SDE does not change over time,it only describes a variable that changes over time.Since (b)is true,(c)is not.The Black-Scholes formula is a solution to a specific partial differential equation (PDE)that is derived from the SDE for stock prices.
2
Consider a stock that is trading at $50,has a volatility of 0.5,and pays no dividends.The risk-free rate is 4%.If the beta of the stock is 1.1,what is the beta of a 52-strike,one-year call option on this stock?

A)0.55
B)1.1
C)3.3
D)4.4
C
The beta of a call is given by the following equation: C The beta of a call is given by the following equation:   We compute this as follows: > S=50 > K=52 > T=1 > v=0.5 > r=0.04 > beta_S=1.1 > d1=(log(S/K)+(r+0.5*v^2)*T)/(v*sqrt(T)) > d2=d1-v*sqrt(T) > C = S*pnorm(d1)-K*exp(-r*T)*pnorm(d2) > beta_C = beta_S * pnorm(d1)* S/C > beta_C [1] 3.334116 We compute this as follows:
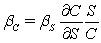
> S=50
> K=52
> T=1
> v=0.5
> r=0.04
> beta_S=1.1
> d1=(log(S/K)+(r+0.5*v^2)*T)/(v*sqrt(T))
> d2=d1-v*sqrt(T)
> C = S*pnorm(d1)-K*exp(-r*T)*pnorm(d2)
> beta_C = beta_S * pnorm(d1)* S/C
> beta_C
[1] 3.334116
3
Given that Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)  and Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)  ,what is Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)  ?
(a) Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)
(b) Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)
(c) Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)
)
(d) Given that   and   ,what is   ? (a)   (b)   (c)   ) (d)
C
4
Which of the following is not a characteristic of a price process Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative. that follows a geometric Brownian motion (GBM)?
(a) Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.
Is an exponential function of a linear Ito process
Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.
,where
Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.
And
Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.
Are constants.
(b) Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.
Is normally distributed.
(c) Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.
Is a continuous process,i.e. ,there are no market "gaps."
(d) Which of the following is not a characteristic of a price process   that follows a geometric Brownian motion (GBM)? (a)   Is an exponential function of a linear Ito process   ,where   And   Are constants. (b)   Is normally distributed. (c)   Is a continuous process,i.e. ,there are no market gaps. (d)   Is non-negative.
Is non-negative.
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
5
Given that Given that   and   ,what is   ? (a)   (b)   (c)   (d)  and Given that   and   ,what is   ? (a)   (b)   (c)   (d)  ,what is Given that   and   ,what is   ? (a)   (b)   (c)   (d)  ?
(a) Given that   and   ,what is   ? (a)   (b)   (c)   (d)
(b) Given that   and   ,what is   ? (a)   (b)   (c)   (d)
(c) Given that   and   ,what is   ? (a)   (b)   (c)   (d)
(d) Given that   and   ,what is   ? (a)   (b)   (c)   (d)
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
6
A call option in the Black-Scholes model is a function of the stock price and time,i.e. , <strong>A call option in the Black-Scholes model is a function of the stock price and time,i.e. ,   .Which of the following statements is valid with regards to the change in the option price over time,i.e. ,   ?</strong> A)The expected change   Is not a function of stock volatility-taking expectations eliminates the Wiener process term. B)The expected change over time is not a function of the remaining maturity of the option,only of the amount of time over which the change is examined. C)The expected change in the call price is not a function of the risk-free interest rate but only the growth rate of the stock at the specific point in time. D)None of the above. .Which of the following statements is valid with regards to the change in the option price over time,i.e. , <strong>A call option in the Black-Scholes model is a function of the stock price and time,i.e. ,   .Which of the following statements is valid with regards to the change in the option price over time,i.e. ,   ?</strong> A)The expected change   Is not a function of stock volatility-taking expectations eliminates the Wiener process term. B)The expected change over time is not a function of the remaining maturity of the option,only of the amount of time over which the change is examined. C)The expected change in the call price is not a function of the risk-free interest rate but only the growth rate of the stock at the specific point in time. D)None of the above. ?

A)The expected change <strong>A call option in the Black-Scholes model is a function of the stock price and time,i.e. ,   .Which of the following statements is valid with regards to the change in the option price over time,i.e. ,   ?</strong> A)The expected change   Is not a function of stock volatility-taking expectations eliminates the Wiener process term. B)The expected change over time is not a function of the remaining maturity of the option,only of the amount of time over which the change is examined. C)The expected change in the call price is not a function of the risk-free interest rate but only the growth rate of the stock at the specific point in time. D)None of the above.
Is not a function of stock volatility-taking expectations eliminates the Wiener process term.
B)The expected change over time is not a function of the remaining maturity of the option,only of the amount of time over which the change is examined.
C)The expected change in the call price is not a function of the risk-free interest rate but only the growth rate of the stock at the specific point in time.
D)None of the above.
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
7
Which of the following is necessary in order to solve the fundamental PDE to obtain the price of a derivative security?

A)The utility function of the representative investor trading in that derivative security.
B)The growth rate of the price of the derivative security.
C)The boundary conditions for the payoffs of the security.
D)A benchmark price of a related derivative security that is correlated with the security being priced.
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
8
The fundamental asset pricing partial differential equation (PDE)is used to derive the Black-Scholes formula.Which of the following statements is not true about the fundamental PDE?

A)The PDE depends on the growth rate of the stock.
B)The PDE is independent of the the utility function of the investor buying the option.
C)The PDE is the same for both calls and puts,the only difference being in the boundary conditions.
D)The solution to the PDE is the Black-Scholes option pricing formula.
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
9
Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of   .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put? (a)   (b)   (c)   (d)  .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put?
(a) Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of   .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put? (a)   (b)   (c)   (d)
(b) Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of   .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put? (a)   (b)   (c)   (d)
(c) Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of   .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put? (a)   (b)   (c)   (d)
(d) Consider a stock that is trading at $50.A six-month at-the-money put option on the stock has a price of 2.21 and a delta of   .The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the put? (a)   (b)   (c)   (d)
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
10
Which of the following properties of a put option's beta is most valid?

A)The beta of a put increases as the stock price increases.
B)The beta of a put decreases if the beta of the stock increases.
C)The beta of a put is bounded between <strong>Which of the following properties of a put option's beta is most valid?</strong> A)The beta of a put increases as the stock price increases. B)The beta of a put decreases if the beta of the stock increases. C)The beta of a put is bounded between   ) D)The beta is always positive.
)
D)The beta is always positive.
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
11
Given the following Ito process for a stock: <strong>Given the following Ito process for a stock:   ,what is the expected value of the stock after 3 years if the current price of the stock is $50?</strong> A)$71.67 B)$86.40 C)$91.11 D)$115.82 ,what is the expected value of the stock after 3 years if the current price of the stock is $50?

A)$71.67
B)$86.40
C)$91.11
D)$115.82
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
12
Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process <strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero. ,given <strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero. ?

A)The process has independent increments <strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero.
,for
<strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero.
)
B)Increments are normally distributed.
C)For each <strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero.
,
<strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero.
Is normally distributed with mean zero and variance
<strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero.
)
D)The process <strong>Option pricing in continuous time makes use of Wiener processes.Which of the following is not a property of a Wiener process   ,given   ?</strong> A)The process has independent increments   ,for   ) B)Increments are normally distributed. C)For each   ,   Is normally distributed with mean zero and variance   ) D)The process   Is a symmetric random walk around zero.
Is a symmetric random walk around zero.
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
13
Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes <strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone. are

A)A special case of Wiener processes <strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone.
)
B)Are functions of Wiener processes: in SDE form, <strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone.
)
C)Are functions of Wiener processes: in SDE form, <strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone.
,with the restriction that
<strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone.
And
<strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone.
Have to be constants.
D)Are functions of Wiener processes: in SDE form, <strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone.
,with the restriction that
<strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone.
And
<strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone.
Have to be constants or functions of time
<strong>Option pricing models are based on Ito processes.Which of the following statements best describes Ito processes? Ito processes   are</strong> A)A special case of Wiener processes   ) B)Are functions of Wiener processes: in SDE form,   ) C)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants. D)Are functions of Wiener processes: in SDE form,   ,with the restriction that   And   Have to be constants or functions of time   Alone.
Alone.
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
14
Given that Given that   and   ,what is   ? (a)   (b)   (c)   (d)  and Given that   and   ,what is   ? (a)   (b)   (c)   (d)  ,what is Given that   and   ,what is   ? (a)   (b)   (c)   (d)  ?
(a) Given that   and   ,what is   ? (a)   (b)   (c)   (d)
(b) Given that   and   ,what is   ? (a)   (b)   (c)   (d)
(c) Given that   and   ,what is   ? (a)   (b)   (c)   (d)
(d) Given that   and   ,what is   ? (a)   (b)   (c)   (d)
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
15
Consider a stock that is trading at $50.A six-month at-the-money call option on the stock has a price of 3.45 and a delta of 0.60.The stock volatility is 20%,the risk-free rate is 4%,and the beta of the stock is 1.1.What is the beta of the call?

A)0.66
B)1.1
C)9.56
D)15.94
Unlock Deck
Unlock for access to all 15 flashcards in this deck.
Unlock Deck
k this deck
locked card icon
Unlock Deck
Unlock for access to all 15 flashcards in this deck.